


Generation Alpha Reshapes the Future of Money
Children are earning, saving and investing earlier, prompting banks and financial firms to target a new generation of customers.
PwC finds 86% of children aged 7–14 have their own money.
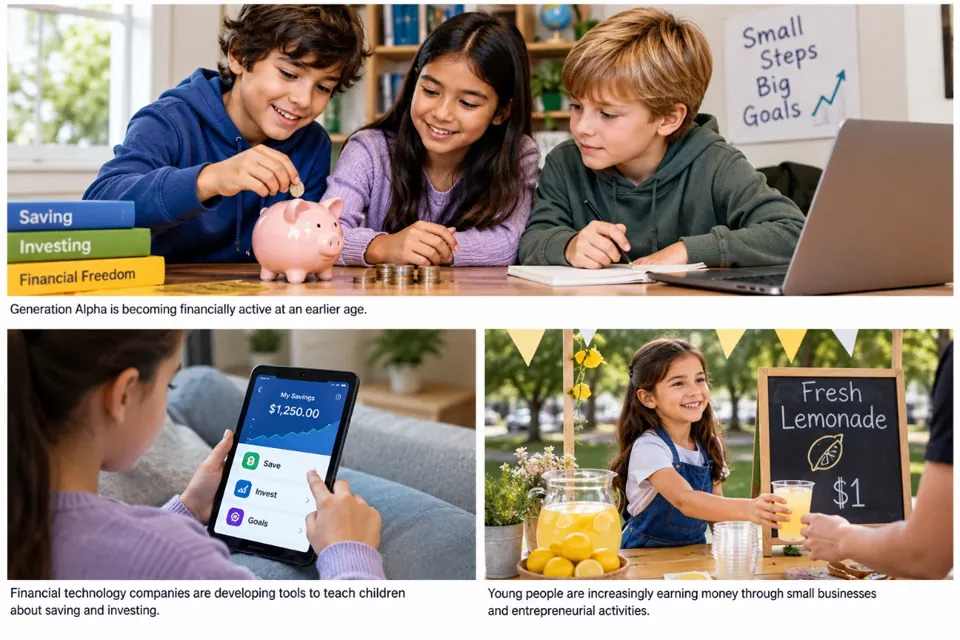
Young entrepreneurs earn through small businesses, online sales and other activities.
Banks and financial companies are developing tools to introduce children to saving and investing.
Generation Alpha is changing how children interact with money and more young people are earning their own income and becoming involved in spending, saving and investing decisions at an early age.
A survey conducted by PricewaterhouseCoopers (PwC) found that 86 per cent of children aged 7 to 14 have their own money, while 97 per cent said they have at least some independence when deciding how to spend it.
The survey, which included more than 1,000 children and their parents during the first quarter of 2026, highlights a shift in children's financial behaviour.
Some children are no longer relying solely on pocket money. They are earning through small businesses, online sales, reselling used products and simple jobs.
Kelly Pedersen, a PwC official, said some parents are surprised by the amount of money their children earn. He cited the example of his 14-year-old daughter, who has generated thousands of dollars through entrepreneurial activities, including a lemonade stand.
Investing Starts Early
The growing financial independence of children is also encouraging parents to consider ways to turn early earnings into long-term savings and investments.
Families are increasingly using savings accounts, educational savings plans and investment accounts for minors. Financial technology companies have also introduced platforms designed to teach children the basics of money management and investing while keeping parents involved in financial decisions.
Noah Kerner, chief executive of Acorns, said managing money involves finding a balance between spending, saving and investing, arguing that these skills can be developed from an early age.
Financial experts, however, stress that children need parental guidance when learning about investments, particularly when dealing with the risks associated with the stock market.
Financial Education Builds Confidence
Fifteen-year-old entrepreneur Belen Woodard is one example of a young person developing financial awareness early.
Woodard began earning money through modeling and later founded the art brand “More Than Peach” at the age of eight. Her products were eventually sold in Target stores, and she also became the author of two children's books.
She said investing initially appeared complicated, but became easier to understand after studying personal finance at school.
Woodard now balances spending on personal interests with saving for larger goals, including a car and future college expenses.
Her mother said giving her children freedom to manage their own money helped develop their independence, talents and entrepreneurial skills.
Parents Play a Key Role
Financial adviser Britney Castro said children learn about money not only through formal lessons but also by observing their parents' everyday financial behaviour.
How parents spend, save and discuss money can influence children's financial habits and attitudes as they grow older.
Banks Eye the Next Generation
Financial institutions are offering families a growing range of products, including savings accounts, educational savings plans and investment accounts for minors.
US options include 529 education savings plans, as well as custodial investment accounts such as UTMA and UGMA, which allow parents or guardians to manage investments on behalf of children until they reach the applicable legal age.
Newer products, including “Trump accounts” or 530A accounts, are also adding another option for long-term savings and investment for children, subject to applicable rules and withdrawal restrictions.
For banks and financial technology companies, the trend represents more than a new way to teach children about money. It also provides an opportunity to build relationships with customers from an early age.
Experts say the long-term value of these accounts is not simply the potential to build wealth. Developing regular saving and investing habits early can help children develop stronger financial behavior as they move into adulthood.
